
Loan programs
Small Balance Commercial Loans
Financing for smaller commercial properties that big banks often pass on.
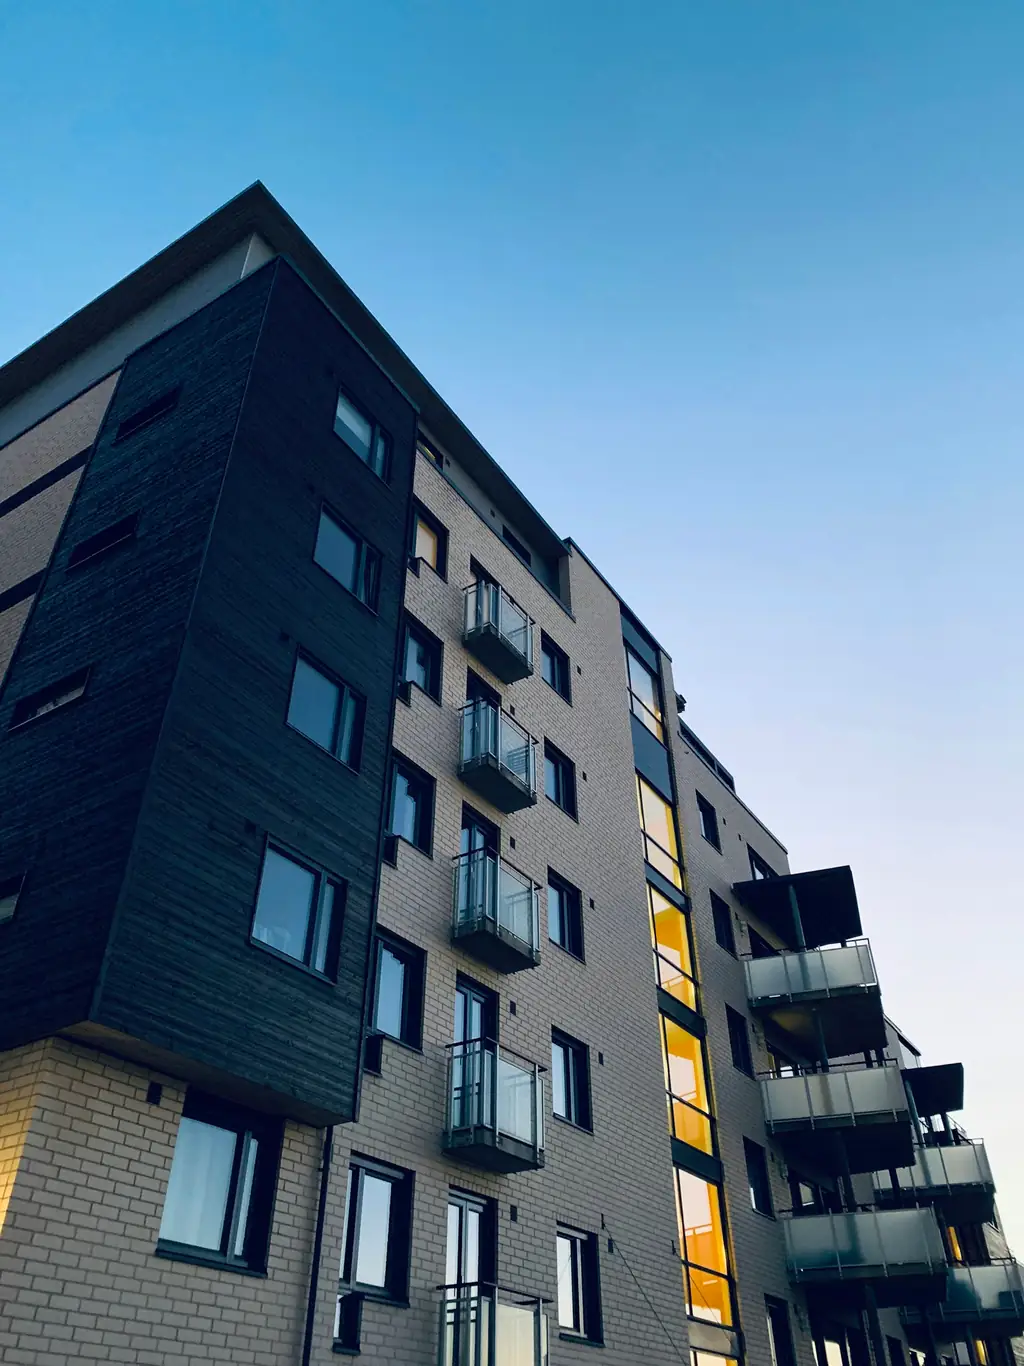
Small balance commercial loans are built for smaller deals: a small apartment building, a corner storefront with apartments above, a small office or a light industrial building. Many large lenders focus on bigger loans, so smaller deals can be harder to place.
We work with lenders that specialize in this size of deal. Some offer different ways to document income, and their guidelines and costs differ from a traditional bank loan. We walk you through those differences before you commit.
Property types
Small multifamily with five or more units, mixed-use buildings, small retail and office, light industrial and warehouse, auto service, self-storage and owner-occupied buildings for your own business.
What lenders look at
The property's rental income and expenses, its condition, your credit and your cash reserves. Some programs focus mainly on the property's cash flow, and some offer limited documentation options for experienced investors. We explain the tradeoffs of each.
Purchase, refinance or cash out
Small balance loans can be used to buy a property, refinance an existing loan, or take equity out of a property you already own to fund your next deal. We review your goals and show you which lenders fit each one.
Questions about Small Balance Commercial Loans
What counts as small balance commercial?
It usually means commercial loans smaller than what large banks and conduit lenders prefer to make. The exact range varies by lender, and we match your deal to lenders that actively want that size.
Can I move from residential rentals into commercial property?
Yes. Many investors start with a small apartment or mixed-use building. Lenders look at your experience with rentals, and we help you present it clearly.
Is this different from a DSCR loan?
DSCR loans usually cover one to four unit homes. Small balance commercial loans cover property with five or more units and commercial space, with their own guidelines.
See what your monthly payment could look like
Type or slide in a home price, the amount you plan to put down, a rate you have been quoted and a term. The estimate updates as you go, and nothing is sent unless you ask David to review it.
Estimated principal and interest
Your estimate appears here
Fill in all four numbers to see it. Prefer to talk it through? Call David at (954) 504-5611.
Estimated principal and interest
$0/ per month
- Down payment
- $0
- Loan amount
- $0
- Interest over the full term
- $0
- Total of all payments
- $0
For illustration only. Not a loan offer. Taxes and insurance not included.
From first call to closing, in four steps
- 01
Start a conversation
Tell David what you are planning. A short call or message is enough to begin.
- 02
Compare your options
David learns your goals and lays out the loan options that may fit, with the tradeoffs explained.
- 03
Apply securely
When you are ready, you apply online. David tells you exactly which documents are needed.
- 04
Get to closing
David keeps you posted through underwriting and is there for questions on closing day.
Other loan programs
Get in touch
Send a message and David will reach out. You can also call or text.
David J Poloney, NMLS #796103
David John Lending Group, NMLS #1958392